Investigating dual-use technology: the war machine doesn’t stop

Over the past year the companies we looked into have continued to expand their military work through record-breaking contracts, acquisitions and dual-use strategies.
Building on our previous research, this piece looks at how technology companies are becoming more embedded than ever in military systems and how increasingly quicker militarisation is spreading across our societies.
Investigating dual-use technology: the war machine doesn’t stop
Since we began publishing profiles as part of our “Investigating dual-use technology and the darker side of innovation” in partnership with Corporate Watch back in September 2025, there have been several developments with the companies that we looked into, which further demonstrate how rapid and drastically the already complex military-industrial landscape is changing:
These trends further blurr the lines between the military and civilian technology sectors and contexts, making it increasingly difficult to sustain the important boundaries that should separate them.
One common element we found across the companies we looked into is their increasingly multinational presence. Meaning they operate through international partnerships, customers and supply chains, so technologies developed in one country can quickly become embedded and made indispensible to the infrastructures of others.
Anduril provides one of the clearest examples of the new defence-technology model: a venture-backed technology company whose central products are AI, software, sensors and autonomous systems rather than simply conventional weapons.
In March 2026, just 4 months after we published our profile on Anduril, the company got awarded a contract with a cumulative ceiling of up to $20 billion by the US Army, covering the integration of current and future commercial technologies which includes its Lattice software, hardware, data and computing infrastructure, merged into a unified Army capability. This contract marks a transition from more than 120 separate procurement actions for Anduril’s commercial solutions to consolidating them into a single contractual framework. This eliminates charges on subcontracts and reduces procurement timelines, compared to the the previous contractual framework we looked at.
Anduril’s expansion is also a clear example of how technology platforms can become part of defence ecosystems far beyond the country in which they were developed, and Australia’s relationship with Anduril shows exactly this. What started as Ghost Shark, an autonomous submarine programme in 2022, subsequently became a major Australian weapons programme. In September 2025 Australia committed A$1.7bn over five years for production, maintenance and further development of dozens of autonomous submarines. The Sydney factory is very much up and running, with more than 40 Australian companies involved in the supply chain which comes to show just how quickly Anduril became so entrenched within the country.
In the UK, the British army announced that it wants to “double its lethality by 2027 and triple it by 2030” - an extremely near future - and that “one way it’s hoping to achieve this is by using something called Lattice”.
As part of the same announcement, Anduril UK’s General Manager Rick Deake bragged that the software was going to “massively speed up the British Army’s ‘kill chain’”:
The beauty of software like Lattice means we can integrate those [military systems] natively and speeding up decision cycles in what we call kill chains, again, to help the Army become more lethal.
Anduril UK’s General Manager Rick Drake
Source: Forces News
In June 2026, the polish Prime Minister announced the signature of an agreement according to which Poland will launch the assembly in Poland, and, in later stages, the production, of autonomous long-range (up to 900 km) Barracuda-500 cruise missiles. This agreement is the first of this kind in Europe. Since then, a broader arrangement involving Poland, Latvia, Estonia and the US was signed jointly produce weapons for NATO’s eastern flank. This agreement aims to make Poland the main production center of the B500M system in Europe.
In July 2026 NATO itself awarded Anduril one of three contracts for the Enhanced Air Command and Control (eAirC2) programme. Anduril is currently deploying Lattice inside the NATO environment for evaluation, where it will integrate things such as air-traffic control, surveillance and force management.
In August May 2026 it was reported that, the Dutch Ministry of Defence awarded Anduril a counter-UAS contract involving integrated air-defence capabilities built around Lattice. The Netherlands company said the system went from contract signing to initial operational capability in less than a month, which shows the company’s appeal to governments seeking rapidly deployable technology. There is also evidence of Anduril equipment becoming embedded in Dutch military communications systems. An EU procurement record from August 2026 lists a €3.05m contract involving Anduril’s Voyager family.
Anduril has also reportedly marked Israel as a key market and its collaboration working with Israeli firms like Elbit could arguably provide additional distribution channels of its “tried and tested” products to foreign armies.
What is worrying about Anduril is more than the huge contracts we see around the globe, or even than the company’s annual goals are set around maximising lethality. That same company, as we reported, does not appear to have standalone ethical, human rights or responsible AI policy like most other big companies in the tech and arms sectors have.
The company’s path illustrates the movement of a private technology company from the contractor realm deeply into the information architecture of militaries around the world. This represents a significant shift in the relationship between the contractor and the state, with potential profound implications in the power dynamics: the businness moves from supplying particular pieces of hardware to controlling the software and data infrastructure through which states perceive the world.
Shield AI illustrates a different but related development: the attempt to make autonomy itself a scalable technological platform.
In March 2026, Shield AI announced it received a 1.5 billion Series G funding round, giving the company a post-money valuation of $12.7 billion, alongside $500 million in fixed-retur preferred-equity financing.~ The same announcement mentions the acquisition of Aechelon Technology, specialising in simulation and synthetic environments. The acquisition of simulation technology is a reflection of how autonomous systems depend upon data, modelling, simulation and testing environments besides the physical hardware.
The company subsequently reported that in FY26 it had doubled orders and revenue year-on-year, expanded deployment of its V-BAT system internationally, and was testing its Hivemind autonomy technology across 30 classes of vehicles and new platforms and missions.
Shield AI is not simply producing an autonomous system bound to a specific drone, it is developing an AI platform intended to operate across multiple types of vehicles. The expansion of Shield AI therefore concerns an entire technological ecosystem surrounding autonomous decision-making. It develops dual-use autonomy software that aims to be both platform-agnostic and deployable across different types of unmanned systems and security applications.
Airbus is a totally different example of dual-use technology provider because it is a much larger, diversified and established aerospace company rather than a newer defence-tech startup.
In April 2026, Airbus Defence and Space CEO Michael Schoellhorn argued for a European “combat cloud” connecting different aircraft and military systems. The idea behind it being that future military capability depends on networked systems sharing information rather than individual platforms operating independently.
In June 2026 the European Investment Bank commited €3 billion to Airbus including an initial €1 billion loan. The funding is intended to support Airbus’s investments through 2030 across commercial aviation, defence, security and technology and Reuters described it as the EIB’s largest corporate loan to date.
The same month Airbus signed a preliminary agreement with Japan’s Kawasaki Heavy Industries to explore a Japanese variant of the Eurodrone, potentially adapted for maritime anti-submarine warfare using Japanese sensors and weapons. The Eurodrone is a European programme involving France, Germany, Italy and Spain, and Japan has been an observer since 2023.
Airbus and Thales Alenia Space (a joint venture of Thales and Leonardo) were selected to lead on what is to become IRIS², Europe’s secure satellite communication system. Airbus is to produce at least 66 satellites in what is an effort to create an alternative to non-European similar programs such as Elon Musk’s SpaceX and Thales Alenia Space will according to the company supply government payloads for 330 of IRIS²’s low-Earth-orbit satellites. IRIS² is a public-private partnership intended to provide infrastructure for governmental, commercial and security applications simultaneously.
Airbus represents something like the “infrastructuralisation” of dual-use technology: civilian and military purposes being increasingly incorporated into the same technological systems from the outset. And in this case, Airbus operates across multiple countries, European programmes and using multiple distinct sources of funding. As such these infrastructures also cross national boundaries with ease.
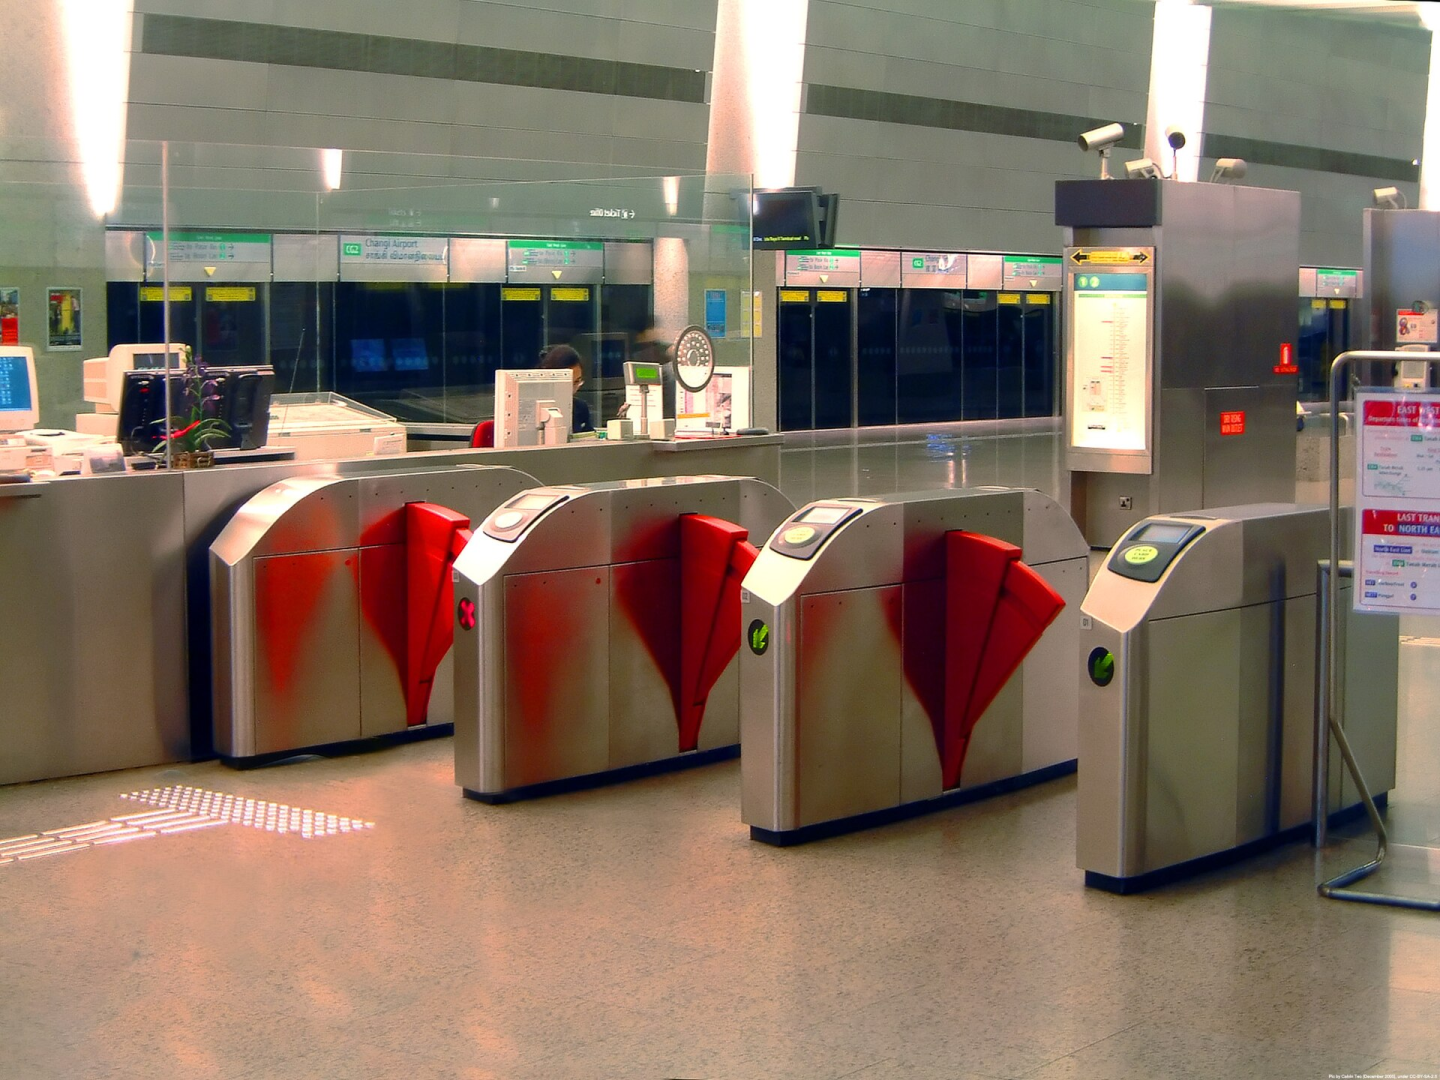
Thales is another distinct example that demonstrates that technology doesn’t need to be a weapon to contribute to militarisation. Thales markets a diverse range of products from automated border checks to biometric identification, drone surveillance, cyber-surveillance and public and national security.
In July 2026, the company announced an the signature of a tender-offer agreement to acquire Exail in a transaction valuing the company at approximately €3.9 billion. Exail brings expertise in autonomous maritime systems, robotics and navigation.
In August 2026, Thales announced that it had completed Phase One qualification under U.S. National Institute of Standards and Technology (NIST)'s FastCAP Programme testing for mobile contactless fingerprint capture, a technology aiming to allow fingerprints to be captured using imaging rather than traditional physical sensores.
Thales’ recent milestones further demonstrate that defence companies are not simply developing new technologies internally; they are acquiring specialist capabilities in robotics and autonomy and incorporating them into much larger military-industrial structures.
Thales is heavily present in the civilian sphere as its activities extend into digital identity, biometrics, transportation, cybersecurity and other civilian infrastructures and as such exemplifies s how military and security technologies can become embedded in systems that people encounter in ordinary civilian life.
Israel Aerospace Industries (IAI) is yet another company making the relationship between military and civilian technology unusually explicit and two-ways.
In 2025, IAI established its Dual Use New Business unit, whose purpose is to identify technologies developed for defence applications and transform them into independent civilian ventures. Its stated areas include AI-based perception and decision support, autonomy, robotics, advanced sensing, cybersecurity, secure communications and space technologies. IAI describes the process as moving from “defence validation” to “commercial value”.
In July 2026, IAI announced a joint project with Israel’s Ministry of National Security, Israel Innovation Authority, Technion and Fire and Rescue Authority to use an IAI APUS 25 drone, infrared/optical sensors and AI to detect wildfires. The drone autonomously scans hundreds of square kilometres, identifies anomalous heat signatures and transmits the location of a suspected fire to the emergency-services command centre. A firefighter defines the search area and the drone then conducts the surveillance autonomously for four to five hours. The system combines autonomous aerial surveillance, electro-optical/infrared sensing and AI analysis. These same components that are here developed or deployed for civilian monitoring could be repurposed in security or military contexts.
IAI develops a wide range of technologies that range from quantum computing, to medical diagnostics, railway safety, sustainable shipping to agriculture. The company presents these as technologies originating in demanding defence applications and subsequently adapted for civilian markets. This reverses the familiar narrative in which civilian innovation is adopted by the military. Here the trajectory is explicitly the other way around.
“Quantum Computing, Medical Diagnostics, Sustainable Shipping – What Do They Have in Common? They all build on technologies IAI originally developed to meet demanding defense challenges, now transformed into scalable civilian ventures”
Source: IAI website
This makes recent comments by IAI chairman and CEO Boaz Levy particularly striking. In September 2026, Levy described a future battlefield requiring highly advanced sensing and “very large data pools” for AI systems to analyse. He gave the example of radar observing the same area over many years, allowing AI to identify changes and infer what might happen next. He said IAI is already building these databases and developing specialist expertise to integrate AI into operational systems. Additionally he described a future in which the military is not the only actor operating within the same information environment. He referred to civilians, security forces, rescue services, hospitals and banks as potentially relying on the same database and data network. In his vision, an ambulance, rescue helicopter and military force would operate from the same situational picture, with sensors, autonomous systems and weapons communicating through a common information pool.
“There are civilians, security forces, rescue forces, hospitals, banks. Everyone relies on the same database. The data must flow from the same information pool to everyone, and at any given moment, for any given scenario, the system must find the optimal response based on the sensors and the effectors or munitions it possesses.”
Boaz Levy (IAI chairman and CEO) for the Jerusalem Post
This is particularly relevant as it makes explicit a tendency visible across the other companies: the convergence of military and civilian systems is increasingly occurring at the level of data and infrastructure, rather than simply hardware.
Taken together, these developments show various forms of militarisation of tech over the past year. Anduril demonstrates the rapid incorporation of a private AI company into major military infrastructure; Shield AI demonstrates the scaling and financing of autonomous military AI; Thales demonstrates the acquisition of robotics and autonomous systems by an established defence company and normalisation of technology in civilian contexts; Airbus demonstrates infrastructure designed simultaneously for governmental and commercial purposes; and IAI demonstrates the deliberate conversion of defence technologies into civilian ventures.
The common thread is therefore the emergence of an increasingly interconnected technological ecosystem in which capital, data, AI, sensors, civilian infrastructure and military capabilities reinforce one another to be as deadly as possible. From a privacy perspective, this creates a particularly important question: when the same technological infrastructure can serve hospitals, banks, emergency services, commercial actors and military forces, where exactly is the boundary between civilian and military data, and who is responsible for determining when that boundary has been crossed?
The multinational character of these companies adds another layer to this problem, since technologies, companies and infrastructures increasingly operate across borders. But the central concern remains the same: the boundaries between civilian and military, public and private, and commercial and security technologies are becoming increasingly intertwined, while the mechanisms for scrutinising those relationships are not developing at the same speed.